
No, you do not need every add-on in car insurance. The right covers depend on your car’s age, your city, how often you drive, where you park, and how much repair cost you can handle yourself.For many Indian drivers, zero depreciation cover, engine protection add-on, roadside assistance, and return to invoice can be worth paying for in the right situation. But if you drive rarely, own an older car, or keep a tight budget, some add-ons may add premium without adding much real value.Think of a hatchback parked outdoors in Mumbai monsoon traffic versus a second car used only on weekends in Pune. Their risks are not the same.
Pick add-ons for likely losses, not for every possible fear.
This guide helps you judge which covers are useful, which are optional, and when to skip them.
Start here: choose add-ons based on your car, city, and driving pattern
Add-ons are worth paying for only when they match the risks your car actually faces.Start with four filters, not a long feature list. A newer car usually benefits more from extra protection because repair bills and part costs are higher, while an older car may not justify every add-on.
- New vs old car: newer cars often suit zero depreciation cover; older cars need stricter cost-benefit thinking.
- Daily commute vs occasional use: more road time means more chances of dents, breakdowns, and claims.
- Flood-prone roads or tight parking: monsoon waterlogging, bumper-to-bumper traffic, and street parking raise damage risk.
- Claim budget: if you do not want big out-of-pocket expenses, stronger add-on support makes sense.
Take a 2-year-old hatchback in Mumbai used daily for office travel and monsoon driving. That owner may prioritise engine protection add-on, roadside assistance, and consumables cover, while someone with a 9-year-old weekend car in Pune may skip most extras.
Buy for probable risk, not for every possible problem.
Once you narrow the likely risks, check insurer policy wording and exclusions before choosing.
Car insurance: the add-ons that usually deliver the most value
In car insurance, a few add-ons tend to offer outsized value because they reduce the claim surprises owners face most often.Think of a Mumbai or Bengaluru driver dealing with bumper-to-bumper traffic, waterlogged roads, tight parking, and regular small damage. In that setting, the right add-on is less about “more cover” and more about avoiding the biggest out-of-pocket costs. Exact scope, exclusions, and claim conditions will still depend on insurer policy wording and IRDAI-linked rules.
Pick add-ons that match your real driving risk, not every option shown on the quote page.
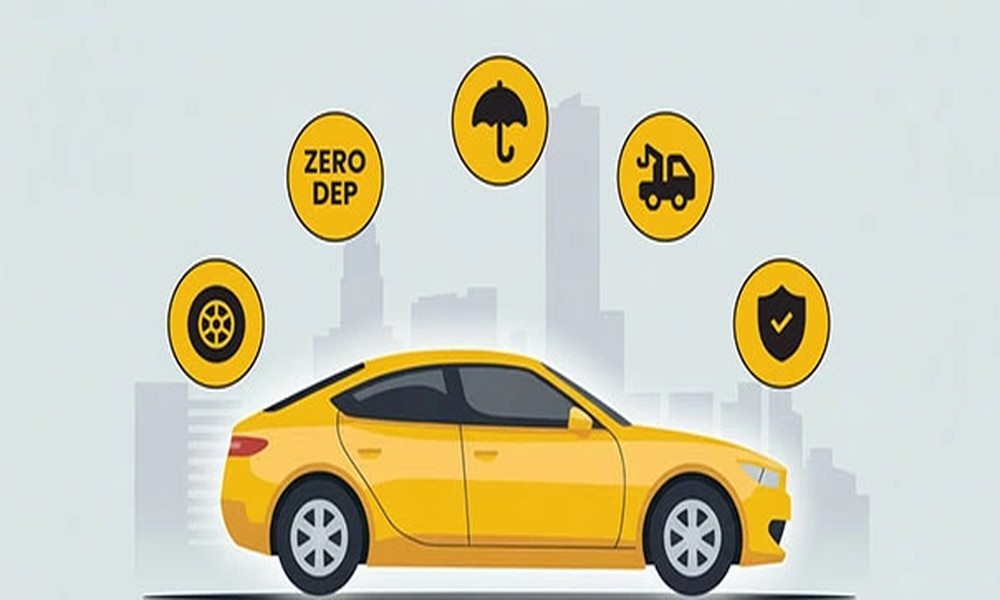
Here is a quick comparison of the covers that often matter most:
- Zero depreciation cover: New cars, city-driven cars, frequent traffic exposure
- Engine protection add-on: Flood-prone cities, monsoon-heavy zones
- Roadside assistance: Daily commuting, highway trips, emergency support needs
- Return to invoice: New or high-value cars
- Consumables cover: Owners who want fewer repair-bill surprises
A closer look:
- Zero depreciation cover: Helps you avoid depreciation cuts on replaced parts during a claim. High value for new cars and city-driven hatchbacks or SUVs that face frequent panel, bumper, and mirror damage.
- Engine protection add-on: Covers engine or gearbox damage after water ingress or related loss, where a basic policy may not help. Situational but very useful in flood-prone cities and monsoon-heavy zones.
- Roadside assistance: Helps with towing, battery jump-start, flat tyre support, and breakdown help. Strong value for daily commuters, highway users, and people who do not want to negotiate local towing in an emergency.
- Return to invoice: Can bridge the gap between IDV and invoice value in total loss or theft. Best for new or high-value cars.
- Consumables cover: Pays for items like engine oil, nuts, bolts, grease, and coolant used in repairs. Useful if you want fewer small claim-time bill shocks.
When an add-on may not be worth the premium
That said, more cover is not always better. An add-on may be poor value if the extra premium is higher than the benefit you are likely to use.Add-ons help when they match your real risk, but some can be poor value for older cars, lightly used cars, or owners who already get similar support elsewhere.If your car is 8-10 years old, paying extra for return to invoice may make little sense because claim value is already limited by age and insured value. If you drive only on weekends and keep the car in gated parking, broad roadside assistance may be less useful than for a daily city commuter.
Compare the likely claim benefit with the extra premium, not just the feature list.
It depends on your usage and city conditions. Before adding anything, check:
- car age and market value
- annual kilometres driven
- flood, traffic, and parking exposure
- duplicate cover from warranty, RSA membership, or credit card benefits
This simple filter can help you avoid paying for protection that sounds good but rarely helps in your situation.
But wait: do add-ons mean every claim will be fully paid?
No, add-ons improve your payout chances, but they do not mean every claim will be paid in full.
Add-ons sit on top of the base policy, so exclusions, deductibles, limits, and paperwork still matter.
This is where many buyers get confused.Myth: zero depreciation cover means every damaged part is covered. Reality: claim approval still depends on policy wording, excluded situations, claim process, and whether the part or event is actually included.For example, if your car stalls in a Mumbai waterlogged street, an engine repair may not be paid unless you also have the right engine-related cover and follow the insurer’s claim steps. The same applies to tyres, consumables, delayed reporting, drunk driving, or using the car outside policy terms.Before buying, check:
- inclusions and exclusions
- compulsory and voluntary deductibles
- claim documents and timelines
- insurer disclosures guided by IRDAI rules
That small check avoids big claim surprises later.
Use car insurance renewal to recheck what you actually need
The best time to review add-ons is during car insurance renewal, because your usage, city, and car age may not be the same as last year. A hatchback used daily in Mumbai traffic and monsoon parking faces different risks than a car now driven only on weekends in Pune.Renewal is not a repeat purchase. It is your chance to keep what proved useful, drop what did not, and adjust cover based on real experience.Use this quick check:
- Did you make any claims last year, and for what type of damage?
- Is the current IDV still reasonable for your car’s age and market value?
- Have you moved to a flood-prone, theft-prone, or high-traffic area?
- Is the car now old enough that some add-ons offer weaker value?
- Did any past add-on actually help at claim time, as per insurer policy wording and exclusions?
Review, then rebuild your mix instead of blindly renewing everything.
What to do next: pick 2-4 add-ons, then compare the final premium
Once you know your risk and know which covers tend to matter most, keep the final decision simple. Shortlist only 2-4 add-ons that match your real risk, then compare the total premium and policy wording before you pay.Use this order:
- Assess your risk: city traffic, monsoon flooding, street parking, highway trips.
- Pick high-value covers that fit that risk.
- Check exclusions, claim limits, and deductibles in the insurer policy wording and IRDAI-linked guidance.
- Compare the final price, not just the base plan.
For example, a Mumbai hatchback owner may prioritise zero depreciation cover, engine protection add-on, and roadside assistance. Buy only when the extra cost clearly matches the protection.
Conclusion
The best add-ons are not the most add-ons, but the ones that match your real risk. A Mumbai hatchback used daily in monsoon traffic needs different protection than a rarely driven second car.Check policy wording, exclusions, and claim limits before purchase or renewal, then pay only for covers you can clearly justify.